Quick answer: A Florida remodel touches three things at once: resale value, your homeowners insurance premium and your property tax assessment. At resale, most projects return less than they cost. The 2025 Cost vs Value report for the South Atlantic region shows a midrange bath remodel recouping 75.3% of its cost and a midrange major kitchen remodel 50.2%. Roof, window and door upgrades can qualify for windstorm discounts, which Florida law requires insurers to build into their rates. On a homestead, improvements are added to the assessment at just value on the first January 1 after they’re substantially complete. And in a flood zone, work that reaches 50 percent of the structure’s market value counts as a substantial improvement under federal flood rules.
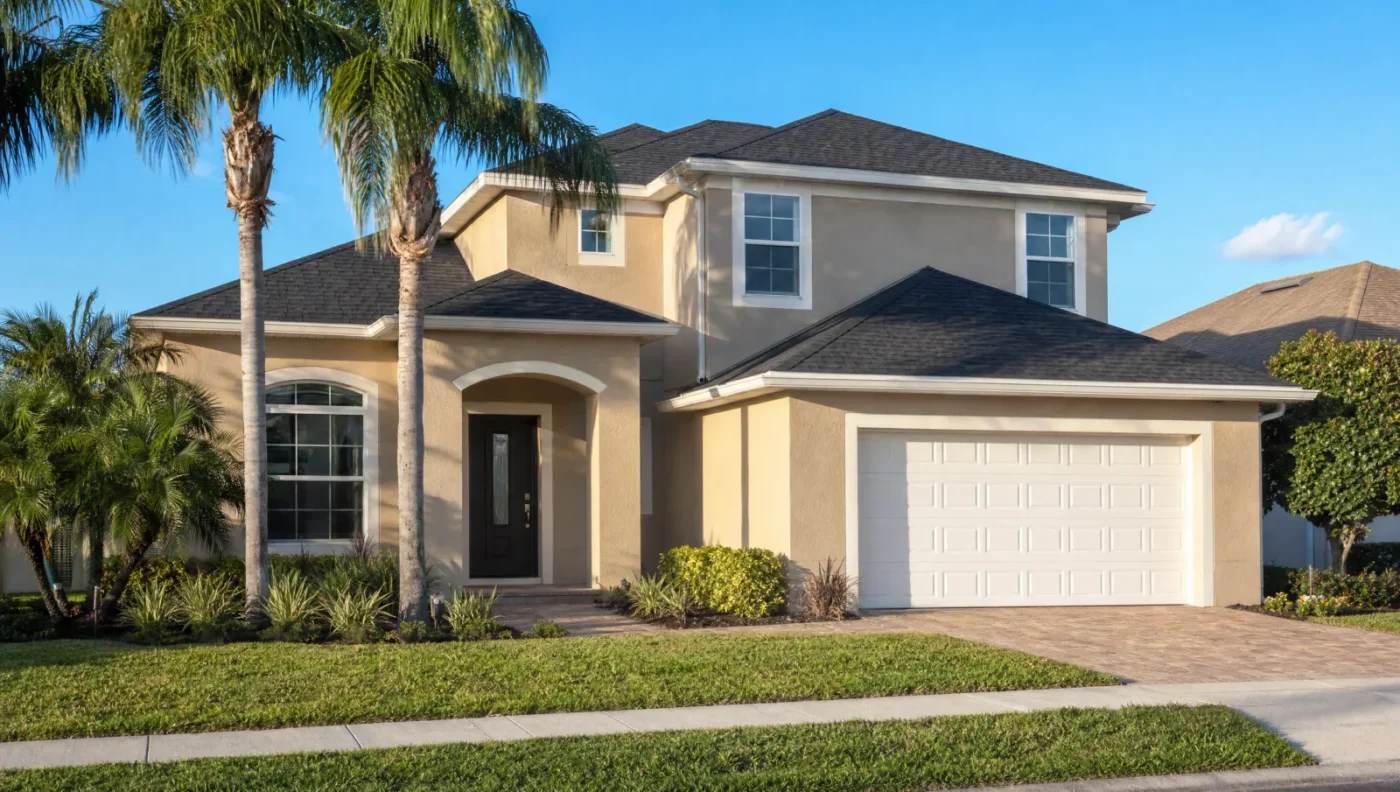
Most remodeling advice stops at resale. In Florida, one project can also show up on the wind mitigation form your insurer reviews, on the property appraiser’s roll and, in a mapped flood zone, in the county’s floodplain review. This guide takes each one in turn, then looks at the projects that move value and insurance together. The figures come from Florida statutes, federal regulations, the Cost vs Value report and the other sources listed at the end, checked in September 2026.
Does Remodeling Increase Home Value in Florida?
Usually, but most projects cost more than the value they add, and exterior replacements return more than big interior remodels or additions. The Cost vs Value report compares the typical cost of 28 remodeling projects with the value they hold at resale across 119 U.S. markets. Its South Atlantic region includes Florida markets such as Miami, Jacksonville, Sarasota and Fort Myers.
| Project | Scope | Cost recouped, South Atlantic (2025) | Cost recouped, national average (2025) |
|---|---|---|---|
| Garage door |
Replacement | 227.7% | 267.7% |
| Entry door |
Steel replacement | 219% | 216.4% |
| Minor kitchen |
Midrange remodel | 109.2% | 112.9% |
| Windows | Vinyl replacement | 82.6% | 75.5% |
| Bath remodel |
Midrange remodel | 75.3% | 80% |
| Asphalt roof |
Shingle replacement | 69.9% | 67.5% |
| Metal roof |
Replacement | 56.5% | 50.1% |
| Major kitchen |
Midrange remodel | 50.2% | 50.9% |
| Primary suite |
Midrange addition | 35% | 32.3% |
Every row comes from the Cost vs Value Report 2025 South Atlantic region page. Cost recouped is the resale value the report assigns to a project divided by its total job cost, so 75.3% means the work adds back about three quarters of what it cost. For kitchens specifically, see whether a kitchen remodel adds home value in Tampa Bay.
Several of the top performers double as hurricane protection in Florida. The My Safe Florida Home program lists window upgrades and exterior door upgrades, including garage doors, as improvements that make a home more hurricane-resilient, and opening protection is one of the features on the state’s wind mitigation inspection form.
How Does Remodeling Affect Homeowners Insurance in Florida?
Making a home more wind resistant can lower a Florida homeowners premium, while adding square footage or upgrading finishes can raise the coverage you need. Florida law drives both.
Wind mitigation discounts are written into Florida law
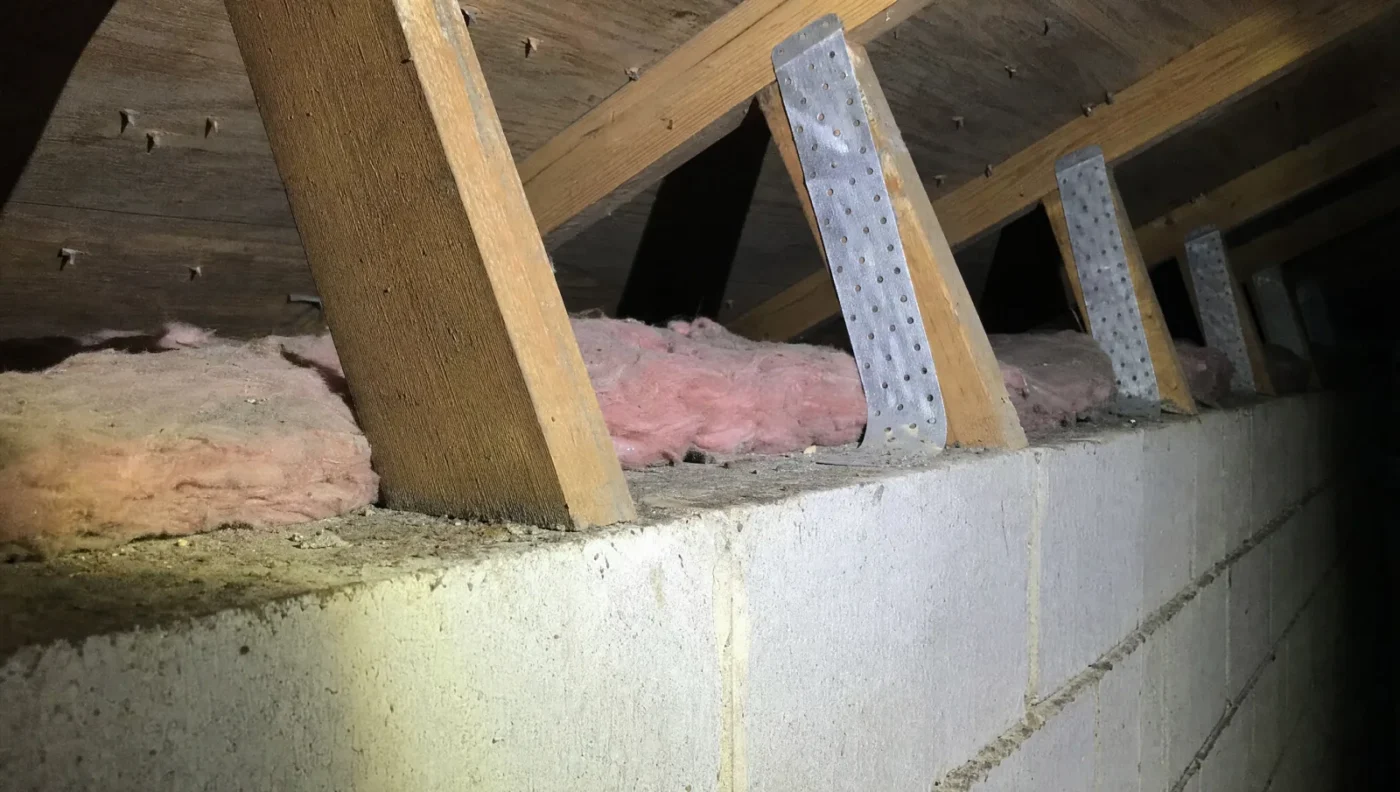
Florida Statutes section 627.0629 requires residential property insurance rate filings to include actuarially reasonable discounts, credits, other rate differentials or deductible reductions for homes with construction techniques or features shown to reduce windstorm loss. Those features include roof strength, roof covering performance, roof-to-wall strength, opening protection, and window, door and skylight strength. Since October 1, 2023, insurers covered by the statute have had to post their hurricane mitigation discounts on their websites.
The wind mitigation inspection is how an insurer sees the upgrade
Insurers identify these features through the Uniform Mitigation Verification Inspection Form. The Florida Office of Insurance Regulation updated it to OIR-B1-1802 (Rev. 04/26), effective April 1, 2026. The form covers features such as the building code, roof covering, roof deck attachment, roof-to-wall attachment, secondary water resistance and opening protection, and FORTIFIED Home Roof, Silver and Gold certificates now qualify for their own mitigation items on it. Citizens Property Insurance Corporation accepts the older version only if it was completed within the five years before April 1, 2026 and the structure hasn’t been altered. The My Safe Florida Home program offers free wind mitigation inspections, and you can share the report with your insurer to make sure you’re getting every available credit on the hurricane portion of your premium.
Replacement cost coverage is capped at the policy limit
Before issuing a homeowners policy, a Florida insurer has to offer replacement cost coverage on the dwelling, up to the policy limits. It also has to offer coverage for the extra cost of complying with current laws and ordinances, which the policyholder can limit to 25 percent or 50 percent of the dwelling limit. If a kitchen, bath or addition raises what it would cost to rebuild the house, ask your agent whether the dwelling limit still fits the home.
What Does a Roof Replacement Change for Value and Insurance?
In Florida, replacing a roof touches more than any other single project, because the building code, the wind mitigation form and insurers’ roof-age rules all hinge on it. At resale, an asphalt shingle roof replacement recoups 69.9% of its cost in the South Atlantic region and a metal roof 56.5%.
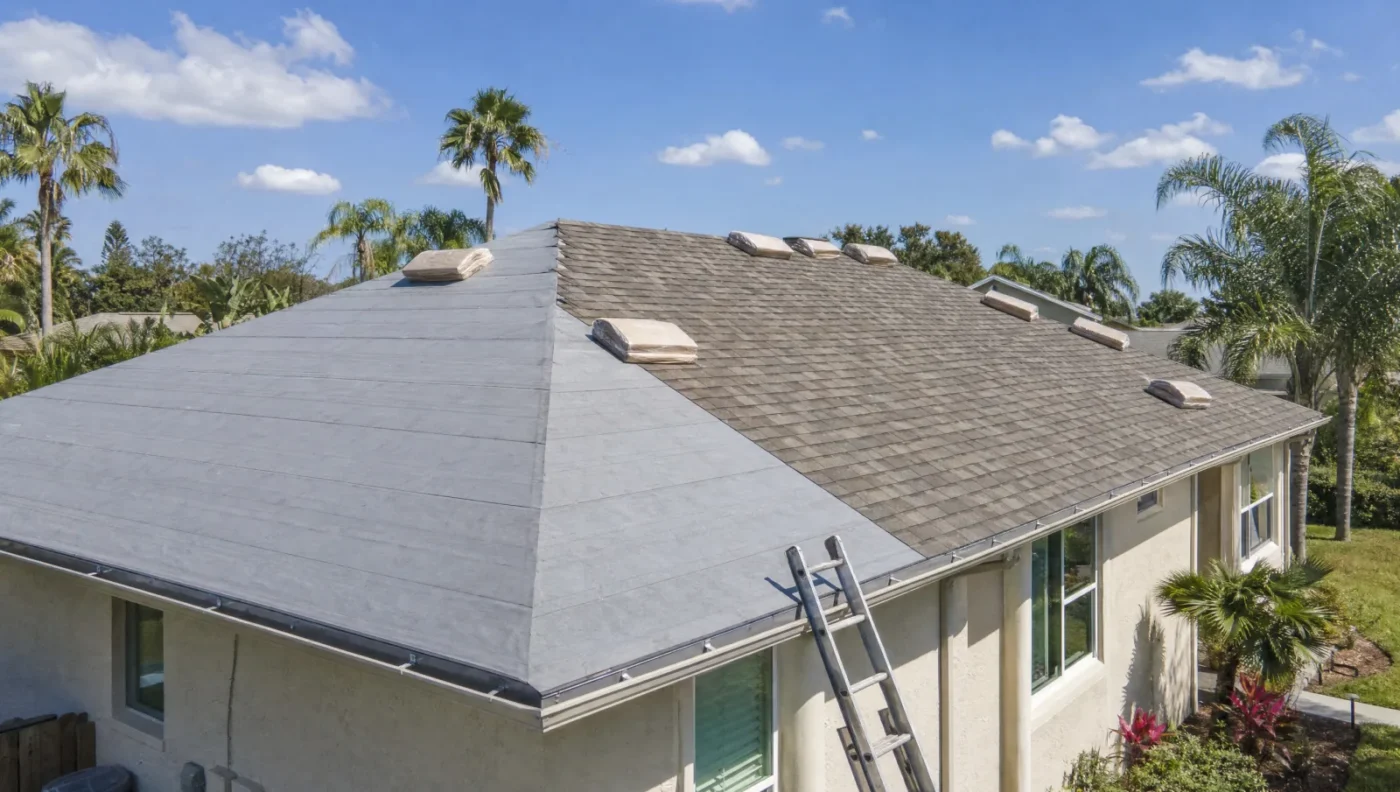
- Code sets part of the scope. For site-built single-family homes, Florida Statutes section 553.844 requires a roof replacement to include a secondary water barrier and to improve or correct the roof-decking attachment and fasteners. The wind mitigation form lists these as secondary water resistance and roof deck attachment.
- The 25 percent rule has an exception. Normally, once 25 percent or more of a roof is repaired, replaced or recovered, the whole roof has to be brought up to the current code. If the existing roof was built, repaired or replaced to the 2007 Florida Building Code or later, only the section being worked on has to meet the current code.
- Roof age resets on a full replacement. A Florida insurer can’t refuse to write or renew a homeowners policy solely because the roof is less than 15 years old. For a roof 15 years or older, the insurer has to allow an inspection by an authorized inspector, and if it shows at least 5 years of useful life left, the insurer can’t refuse coverage based solely on roof age. Roof age is counted from the last date 100 percent of the roof surface was built or replaced to the code in effect at that time.
Will Remodeling Raise Property Taxes on a Florida Homestead?
It can, because new work, added space and upgrades on a homestead are assessed at just value, outside the annual cap. Florida Statutes section 193.155 limits a homestead’s annual reassessment to 3 percent or the change in the Consumer Price Index, whichever is lower. Changes, additions and improvements are assessed at just value as of the first January 1 after they’re substantially complete.
Storm recovery follows a different rule. When a homeowner replaces homestead property damaged or destroyed by misfortune or calamity, the assessment uses the assessed value from the January 1 before the damage, subject to the cap. That applies when the rebuilt square footage stays within 130 percent of the square footage before the damage, or the total is no more than 2,000 square feet.
What Is the 50 Percent Rule, and When Does It Apply?
The 50 percent rule is the federal flood rule for substantial improvement. It applies when the cost of reconstruction, rehabilitation, an addition or another improvement equals or exceeds 50 percent of the structure’s market value before construction starts. The definition includes structures that have had substantial damage, regardless of the repair work actually performed, and leaves out work to correct identified code violations and alterations that preserve a historic structure’s designation.
In Zones A1-30, AE and AH on a community’s flood map, federal floodplain rules require new construction and substantial improvements of residential structures to have the lowest floor, including a basement, elevated to or above the base flood level. For a coastal bathroom, CMK Construction explains how the 50 percent rule shapes a flood-zone bathroom remodel. Your county floodplain office can tell you whether a home is in a mapped flood zone and how it calculates the structure’s market value.
Which Remodels Help Value and Insurance at the Same Time?
Roof, window and exterior door projects are the most likely to raise resale value and lower the insurance premium together, because they appear both in the Cost vs Value tables and on the wind mitigation form.
- Roof replacement. It recoups 69.9% for asphalt shingles in the South Atlantic region, adds the code-required secondary water barrier and deck attachment work, and resets the roof age insurers rely on.
- Windows and exterior doors. In the region, a garage door replacement recoups 227.7%, a steel entry door 219% and vinyl windows 82.6%, and My Safe Florida Home lists window and exterior door upgrades, including garage doors, among its hurricane improvements.
- Kitchens and baths. A midrange minor kitchen remodel recoups 109.2% and a midrange bath remodel 75.3%. Because the wind mitigation form covers the roof, roof-to-wall attachment, secondary water resistance and opening protection, the insurance effect of a kitchen remodel or bathroom remodel is usually on the dwelling limit rather than a rate discount.
- Additions. A midrange primary suite addition recoups 35% in the region, adds just value to the assessment once it’s finished, and counts toward the 50 percent threshold in a flood zone.
What Should Florida Homeowners Do Before and After Remodeling?
- Check the flood zone first. If the property is in a mapped flood zone, the project’s cost is measured against 50 percent of the structure’s market value, so confirm that number with the county before you finalize the scope.
- Get a wind mitigation inspection before and after. The form covers the roof covering, roof-to-wall attachment and opening protection, and Citizens accepts an older form only when the structure hasn’t been changed.
- Review the dwelling limit with your agent. Replacement cost coverage pays up to the policy limits, and law and ordinance coverage can be set at 25 percent or 50 percent of the dwelling limit.
- Keep permits and inspections on file. Permit and final inspection records show when a roof was replaced and that the work was completed. CMK Construction explains when a Florida bathroom remodel needs a permit.
- Plan for the next January 1. Improvements are assessed at just value as of the first January 1 after they’re substantially complete.
Where CMK Construction Fits
CMK Construction is a Florida State Certified General Contractor (CGC 1516665) and also holds Certified Plumbing Contractor (CFC 1430533), Certified Roofing Contractor (CCC 1336554) and Registered Electrical Contractor (ER 13016498) licenses. The company handles kitchens, bathrooms, room conversions, roofing and storm restoration, designed in-house and built by one licensed team, and every project is fully permitted and inspected.
On a roof replacement, CMK strips the roof to the deck, replaces damaged wood and rebuilds the assembly with drip edge, synthetic underlayment, sealed valleys, architectural shingles, vent boots and ridge caps. After severe weather, CMK’s storm restoration crew documents the damage, meets the adjuster and makes the repairs.
Schedule a free consultation or call (813) 379-2116.
Related reading:
- How Much Does a Whole-Home Renovation Cost in Tampa Bay?
- What Does a Kitchen Remodel Cost in Tampa?
- How Much Does a Bathroom Remodel Cost in Tampa?
Remodeling, home value and insurance FAQ
Does a new roof lower homeowners insurance in Florida?
It can. Florida law requires residential property insurance rate filings to include discounts or credits for roof strength, roof covering performance and roof-to-wall strength. The wind mitigation form lists roof covering, roof deck attachment, roof-to-wall attachment and secondary water resistance among its key features. A full replacement also resets the roof’s age, and insurers can’t refuse coverage just because a roof is less than 15 years old.
Does remodeling raise property taxes on a homesteaded Florida home?
Often, yes. Changes, additions and improvements to a homestead are assessed at just value as of the first January 1 after they’re substantially complete, outside the annual cap of 3 percent or the change in the Consumer Price Index, whichever is lower. Rebuilding after a storm keeps the prior assessed value as long as the square footage stays within 130 percent of the original or the total is no more than 2,000 square feet.
Which remodeling projects return the most at resale in Florida?
Exterior replacements lead. The 2025 Cost vs Value report for the South Atlantic region shows a garage door replacement recouping 227.7%, a steel entry door 219% and a midrange minor kitchen remodel 109.2%, while a midrange primary suite addition recoups 35%.
Does the FEMA 50 percent rule apply to remodeling?
Yes, in a mapped flood zone. Any improvement that costs 50 percent or more of the building’s market value before construction is a substantial improvement. In Zones A1-30, AE and AH, federal rules require communities to have the lowest floor of a substantially improved home at or above the base flood level.
Do I need a new wind mitigation inspection after remodeling?
Yes, if the work changed the roof, windows or doors. The form covers roof covering, roof deck attachment, roof-to-wall attachment, secondary water resistance and opening protection, and Citizens won’t accept an older form if the structure has been altered. The My Safe Florida Home program offers free wind mitigation inspections.
Sources
- Journal of Light Construction, Cost vs Value Report 2025, South Atlantic region
- The Florida Senate, 2026 Florida Statutes, section 627.0629: Residential property insurance; rate filings
- The Florida Senate, 2026 Florida Statutes, section 193.155: Homestead assessments
- eCFR, 44 CFR 59.1, Definitions (substantial improvement)
- My Safe Florida Home, Program home page
- Citizens Property Insurance Corporation, Uniform Mitigation Verification Inspection Form Changes (March 19, 2026)
- The Florida Senate, 2026 Florida Statutes, section 627.7011: Homeowners’ policies; offer of replacement cost coverage and law and ordinance coverage
- The Florida Senate, 2026 Florida Statutes, section 553.844: Windstorm loss mitigation; requirements for roofs and opening protection
- eCFR, 44 CFR 60.3, Flood plain management criteria for flood-prone areas
- CMK Construction, Residential Remodeling
- CMK Construction, Home page
- CMK Construction, Roofing
- CMK Construction, Hurricane and Storm Restoration